

Thursday, March 15, 2012


Wednesday, March 14, 2012
VIX SLIDES AS MARKETS GET COMPLACENT!

As the rally in equity markets continues, let us not forget that we still face headwinds in 2012.
Troubles in the Eurozone, record high oil prices and a possible slowdown in China.......are some of the lingering concerns.
CAVEAT EMPTOR!
Friday, March 9, 2012
GOLD -Volatile times
Gold prices continue to trade rather erratically, and over the past week have corrected below the $ 1700 level, before pulling back slightly.
I continue to be a long term gold bull, and ongoing actions of the world's central banks will continue to support higher gold prices over the longer term.
Here is the Gold Angel image from Jim Sinclair's - JSMINESET.COM
At this stage of Gold's ''bull market'', patience is vital and a steady buy on declines policy is advisable.
I would advise investors to avoid short term trading in this manic market..

Tuesday, January 17, 2012

Saturday, January 7, 2012
INDIAN EQUITIES -DEBT WORRIES SURFACE AS THE ECONOMY SLOWS
As the Indian Economy slows, a number of Indian Corporates may find that they over-stretched themselves while the going was good, and are now saddled with heavy debts to repay.
It's not that borrowing for business expansion is a bad thing in itself, it's just that some over-leveraged Corporates will struggle with debt servicing in 2012.
Some sectors that come to mind are the Airlines, Oil services, Ship- building and infrastructure.

 Investors must keep in mind that although many stocks in these sectors trade at record low valuations, the Risk -Reward ratio may still not favour investors at this stage.
Remember some stocks have been beaten down for well deserved reasons, and investors must analyse their own risk return profiles before jumping in now.
In my view, many companies will need some debt restructuring before they can trurn things around.
This could mean that the banking sector too could take a while to recover, at least until interest rate cuts expected in the near future ease the liquidity concern of some cash strapped corporates.
Invest wisely!
It's not that borrowing for business expansion is a bad thing in itself, it's just that some over-leveraged Corporates will struggle with debt servicing in 2012.
Some sectors that come to mind are the Airlines, Oil services, Ship- building and infrastructure.


Remember some stocks have been beaten down for well deserved reasons, and investors must analyse their own risk return profiles before jumping in now.
In my view, many companies will need some debt restructuring before they can trurn things around.
This could mean that the banking sector too could take a while to recover, at least until interest rate cuts expected in the near future ease the liquidity concern of some cash strapped corporates.
Invest wisely!
Indian Equities - Looking Back at 2011 - PART 2
Here are a couple more articles to round up our look back at 2011!


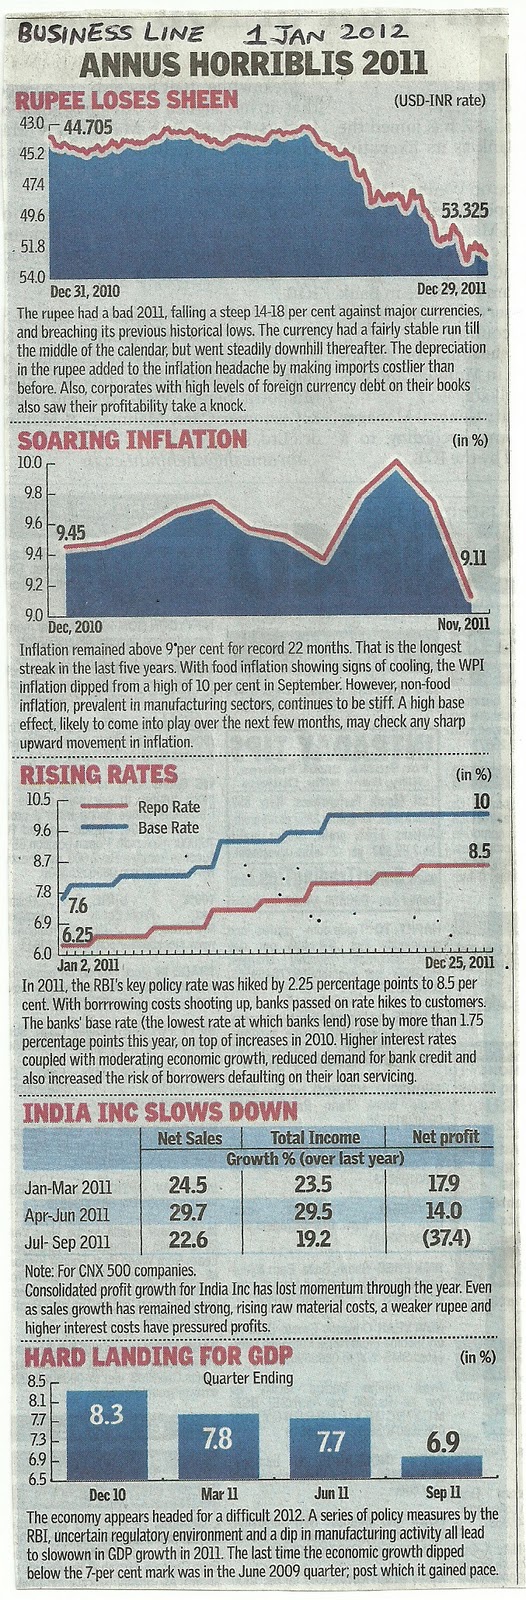
Monday, January 2, 2012
INDIAN EQUITIES - LOOKING BACK AT 2011
Here are some articles from last year that I think are worth a read.
 Indian Equities have been faced with a toxic combination of Policy inaction, high interest rates, a very weak Indian Rupee and waves of instability from western markets, primarily the EU.
The articles below provide some interesting views on the Outlook for 2011. Mukul Pal's contrarian outlook, highlights the point that beaten down sectors that have been written off by Mr. Market could surprise us in 2012!


The articles below provide some interesting views on the Outlook for 2011. Mukul Pal's contrarian outlook, highlights the point that beaten down sectors that have been written off by Mr. Market could surprise us in 2012!


Thursday, December 8, 2011
IS PLATINUM CHEAP RELATIVE TO GOLD ?
Here's a great article from Willem Weytjens of www.profitimes.com on the ongoing discount of Platinum vs Gold.
As the author mentions in the article, platinum may not be cheap at the moment but it certainly appears to be undervalued vs Gold
http://profitimes.blogspot.
Here's an excerpt from his article.

As the author mentions in the article, platinum may not be cheap at the moment but it certainly appears to be undervalued vs Gold
http://profitimes.blogspot.
Here's an excerpt from his article.
"""These
days, gold is trading near all-time highs, while platinum is trading about $700
below its all-time high reached in 2008.
Since 1972, Platinum traded at about 1.35 times the price of Gold on average. Right now, Platinum is even cheaper than gold, trading at only 0.92 times the price of Gold. As we can see in the chart below, this is a rather “rare” situation. It only happened in the early 80′s and for a short time in 1974. In 1972, 2000 and 2008, it even traded as much as 2.30 times the price of Gold (monthly basis).
Since 1972, Platinum traded at about 1.35 times the price of Gold on average. Right now, Platinum is even cheaper than gold, trading at only 0.92 times the price of Gold. As we can see in the chart below, this is a rather “rare” situation. It only happened in the early 80′s and for a short time in 1974. In 1972, 2000 and 2008, it even traded as much as 2.30 times the price of Gold (monthly basis).

Based
on this ratio over the last 40 years, we can say that Platinum is “cheap”
relative to Gold.""""
Watch this space!
Saturday, November 26, 2011
INDIAN RUPEE : FOREX FLUCTUATION & INDIAN POLICY REFORMS
Here is a good article from today's Business Standard Newspaper in Mumbai.
Rupee fall pares India Inc's profit by a fourth in Q2

If the weakness in the INR continues, upcoming FCCB redemptions, USD denominated foreign Currency borrowings and the rising cost of imported raw materials will continue to add to the woes of Indian Corporates in the results of the third quarter.
Many blame the INR weakness on FII selling in the Indian Equity markets.
While FII selling has played its part, I feel the ongoing Government policy malaise and concerns over the Government's Fiscal Deficit continue to weigh down the INR.
Currency downgrades by the Rating Agencies will add to the downward pressure on the INR.
Also, it's about time that the Indian Government gets down to implementing many long delayed reforms.
Some sectors in dire need of reforms
POWER SECTOR - Poor financial health of State Electricity Boards (SEBs) is forcing them to resort to load shedding of power even as Power producers are left with surplus power that they are unable to sell. These SEB's must move towards a market determined pricing of power sold by them to distribution companies.
Merchant Power sales and Power trading are also facing many unresolved policy issues.
Under construction Ultra Mega Power Projects also face uncertainities due to fuel linkages (read: Coal allocation issues and royalty issues on Coal imported from Indonesia).
.
MINING SECTOR - Confusion over a proposed Mining Tax, profit sharing with locals displaced by Mining projects, Land acquisition delays and mining scams and corruption have delayed many Mining & Smelter projects.
.
FERTILIZER SECTOR - Partial implementation of the Nutrient Based Subsidy Scheme (NBS) and the delays in decontrol of Urea pricing have compounded the problems of the sector. Heavily subsidised Urea fertilizer has resulted in farmers opting to use Urea over DAP fertilizer. Excessive use of Urea has upset the balance of soil nutrients and has thus resulted in lower crop yields.
Any further delay in decontrolling Urea fertilizer pricing will add to government subsidies as the government continues to import Urea shortfall from overseas. A weak INR will add to the cost of imported Urea fertilizer.
.
TELECOM SECTOR - The ongoing 2G scandal and corruption cases continue to dominate news in the telecom sector. What the government must take a look at is reforming regulations that will promote consolidation in the Telecom sector. Recent issues of 3G roaming should also be clarified by the TRAI and the government, to avoid any further uncertainty in this sector.
.
AVIATION SECTOR - A combination of ''below cost '' fares by Air India, record high ATF prices, ultra competitive air ticket prices, and record high debt of the airlines themselves has resulted in some serious structural problems in the Indian Aviation sector. FDI limits in Indian Aviation will have to be liberalised and a more viable tax structure on ATF will have to be worked out, if the existing carriers are to survive as going concerns. Perhaps the government will have to look at the development of "Low cost airports'' from which the Low Cost Carriers can operate, given the expensive Landing and Parking Costs at the country's main airports.
.
OIL SECTOR - Massive delays in implementation of a clear and viable Gas Pricing policy is delaying further development of Oil and Gas Blocks in the KG Basin. Until this vital issue is resolved, Fuel Linkage issues of Power & Fertilizer Plants will not be resolved. The longer it takes for this Gas to reach the market, the more will be the delays of construction of new Power and Fertilizer Plants.
Also the" retail fuel pricing - under recovery problem" of the Oil Marketing companies (OMCs) remains unresolved. Massive subsidies on retail fuels sold by the OMCs have weakened their finances over the last decade.
A weak INR+ high Crude Oil price is adding to the under recovery burden of the OMCs.
If the government fails to move to a market determined pricing mechanism for Retail fuels soon, these OMCs will soon need to be bailed out by the government.
.
All in all, it's about time that the government takes a step forward, and gets downto resolving these 'bottle neck' issues that are plaguing the Indian Economy at the moment.
If some of the supply side issues are worked upon, then perhaps the subsequent drop in inflation and an improvement in the government's fiscal deficit targets, will help the INR to regain some lost ground.
Tuesday, November 22, 2011
THE INDIAN RUPEE - WEAKNESS CONTINUES.....
The continuing weakness of the INR vs the USD is starting to worry both investors and regulators alike. Negative FII fundflows in the Equity markets is adding to the weakness of the INR.
At a time when inflation continues to be persistantly high, a weak INR will add to India's already increasing Crude Oil import costs.
 The Equity Markets in India are preparing themselves for forex loss announcements from companies that import their raw materials and those that have large Foreign Currency borrowings.
We are now surpassing levels last reached during the heights of the financial crisis in the first quarter of CY 2009, just after the Lehman Crisis!
Energy and commodity prices were far lower in March 2009 than they are right now; so the Government and especially the Central Bank (R.B.I) will have to come up with some strategy to stabilize if not support the INR at current levels.
WATCH THIS SPACE!
At a time when inflation continues to be persistantly high, a weak INR will add to India's already increasing Crude Oil import costs.

We are now surpassing levels last reached during the heights of the financial crisis in the first quarter of CY 2009, just after the Lehman Crisis!
Energy and commodity prices were far lower in March 2009 than they are right now; so the Government and especially the Central Bank (R.B.I) will have to come up with some strategy to stabilize if not support the INR at current levels.
WATCH THIS SPACE!
Subscribe to:
Posts (Atom)