Friday, December 31, 2010
EURO - OUTLOOK 2011
Thursday, December 30, 2010
Sunday, December 19, 2010
INDIAN EQUITIES : FII & Domestic Institutional Fundflows
Link - Domestic institutions turn cautious, go on selling spree ...
As usual, FII fundflows continue to dictate market direction, but as the above article points out, Domestic Institutional investors - Mutual Funds are booking profits.

Saturday, December 18, 2010
UPDATE : 30 YEAR US TREASURY BOND

Friday, December 17, 2010
A TALE OF TWO INDIAS !
Graft in India - Rotten to the Core? Coping with the aftermath of a massive scam !!!
And who's to say that they are off the mark as far as the story goes.
We have been on a never ending roller coaster of scams.
- IPL - Cricket scam -issues regarding benami -ownership structures of teams
- Commonwealth games scam.
- Adarsh Building scam in Mumbai - Illegal Building on Army land
- Telecom 2G scam - That's a mega one!
- Public Sector bank officials involved in a loans for bribes scam.
- Stock price rigging scam being investigated by SEBI.
- Nira Radia tapes - involving journalists, industrialists etc!
So we have massive wealth disparity, income inequality, corruption, rural poverty, poor infrastructure and then we have on the other hand an ecomnomy that's doing fantastically well, while the world economy is still reeling under the strain of slowing consumer consumption and record debt levels.
.
.
.
.
.
.
.
.
.
.
..
.
.
..
.
..
.
.
.
While its going to be a never ending discussion about the politicians, industrialists and other individuals involved in these scams, there are some facts and lessons that an investor in Indian markets can take away from this mess.
- While the Indian Economy does present a fantastic investment opportunity to both Indian and overseas investors, it can be bumpy ride at times.
- While the Indian government continues to move slowly on / ignore vital issues like wealth disparity, rural poverty, overburdened infrastructure and the poor state of primary education and healthcare facilities across India, they must realise that this economic boom cannot continue unless they start to tackle the above mentioned critical problems and target "inclusive growth".
- Remember to curtail investments to firms where the management has a credible track record and takes care of the interests of all stakeholders concerned - & not just themselves! You may come acoss an interesting investment opportunity, but if the management has a dodgy track record, just stay out!
- If SEBI fails to rein in the Equity market scamsters, it will result in a massive blow to SME (Small and medium enterprises) businesses in India. The SMEs are the ones most affected by these stock rigging scams because a tightening of bank credit across the SME sector will deny working capital loans to many deserving and good quality small cap companies in India
- The incredible progress that has been made by Corporate India has been made inspite of our politicians and not because of them!
- While I'm not condoning the massive, almost blatant and shameless corruption here in India; we live in a world where politicians in most countries are no better than the ones we have here. It may be less blatant but sadly,corruption goes on!
- There is incredible corruption,short termism and lack of leadership in global politics today.As someone rightly said, " The people who want to be in politics are not the people whom you want to be in politics". No politician is willing to fix a problem that he can kick further down the road, an example being the *crazy debt crisis* facing the western world today! Imagine asking consumers who have no savings to start overspending and re- leveraging again - Thats both WRONG & insane!
- Lastly, remember that the prudent investor does not chase an over extended stock market rally. Remember to wait for pull backs and always look to invest in good quality stocks, with managements that have an established track record!
TELECOM SECTOR INDIA : CONSOLIDATION TIME
Link:
All new telcos have less than 50% active users, finds Trai - The ...
The Pre-paid/ Pay as you go segment dominates the mobile phone telecom sector in India.
With record-low tariffs and cut throat competition, telecom companies are hoping to regain earnings traction via 3G services!
Furthermore, we may be headed for a 3G price war as well.

The percentage of active subscribers is far too low in the case of many of the new entrants. Some of the new players will gradually find the current tariffs unviable for their business models, and a consolidation is likely.
This is clearly an overcrowded market. In the meantime, expect the established incumbents to aggressively defend their market share. This will result in reduced profitability in the near term, until an inevitable consolidation occurs/ some players exit the market altogether.
Saturday, November 27, 2010
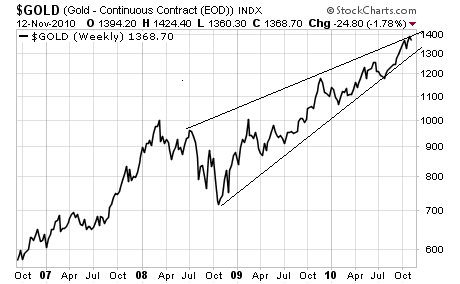
GOLD - TOO FAR TOO FAST?


Wednesday, November 24, 2010
Monday, November 15, 2010
BANANA REPUBLICS ...FINANCIAL CRISES & MEGA BAILOUT PACKAGES
The USD seems to be trying to stabilise, even as gold prices cool off after striking new highs.
Here is a fantastic article that addresses the topic of Banana Republics!
Currency wars / manipulation continue and as bailout packages are announced, many are still asking questions as to who the final beneficiaries of these handouts will be ??
Here's an excerpt from the NY Times article of Nicholas Kristof -
The richest 1 percent of Americans now take home almost 24 percent of income, up from almost 9 percent in 1976. As Timothy Noah of Slate noted in an excellent series on inequality, the United States now arguably has a more unequal distribution of wealth than traditional banana republics like Nicaragua, Venezuela and Guyana.
C.E.O.’s of the largest American companies earned an average of 42 times as much as the average worker in 1980, but 531 times as much in 2001. Perhaps the most astounding statistic is this: From 1980 to 2005, more than four-fifths of the total increase in American incomes went to the richest 1 percent.
That’s the backdrop for one of the first big postelection fights in Washington — how far to extend the Bush tax cuts to the most affluent 2 percent of Americans. Both parties agree on extending tax cuts on the first $250,000 of incomes, even for billionaires. Republicans would also cut taxes above that.
The richest 0.1 percent of taxpayers would get a tax cut of $61,000 from President Obama. They would get $370,000 from Republicans, according to the nonpartisan Tax Policy Center. And that provides only a modest economic stimulus, because the rich are less likely to spend their tax savings.
At a time of 9.6 percent unemployment, wouldn’t it make more sense to finance a jobs program? For example, the money could be used to avoid laying off teachers and undermining American schools.
Likewise, an obvious priority in the worst economic downturn in 70 years should be to extend unemployment insurance benefits, some of which will be curtailed soon unless Congress renews them. Or there’s the Trade Adjustment Assistance program, which helps train and support workers who have lost their jobs because of foreign trade. It will no longer apply to service workers after Jan. 1, unless Congress intervenes.
So we face a choice. Is our economic priority the jobless, or is it zillionaires?
Wednesday, October 20, 2010
CURRENCY VOLATILITY
Here are some charts that tell the whole story. No one seems to want a strong currency!
- The rally in the EUR, JPY and CHF will hurt exporters in Europe, Japan and Switzerland.
- A weak USD meanwhile, will boost US exports.
- The Chinese have thus far resisted any significant appreciation in the Chinese Yuan.
USD CHF : The CHF broke down below parity in its recent rally vs the USD
USD CAD : It came ever so close to testing parity vs the USD
USD JPY : Despite the efforts of the Bank of Japan to weaken the JPY, the JPY continues its relentless upward march.
EUR USD : A weak EUR helped boost Germany's GDP numbers last quarter. the recent rebound in the EUR will surely make life difficult for the Club Med nations
Conclusion:
The USD appears to be oversold in the near term and a counter trend rally is underway. The market is betting on some mega fire power solution from the US Fed at its meeting in November. If QE2 disappoints and the equity markets sell off, the USD could stage a much stronger rally!
The Equity markets have been getting far too complacent about the weak and worrying news data and unemployment numbers in the US.
Fund flows to emerging markets have boosted stock prices across the board and a correction is well overdue. These markets are ''not decoupled from the actions of the US Fed'' and when the tide starts to turn we can expect large fund outflows to have a drastically negative impact on stock prices in emerging economies
Lastly, the rally in Gold prices also appears ripe for correction and consolidation. Silver prices too, are clearly overstretched in the near term. expect lower prices if the USD stages a comback rally. It's not time to be buying the precious metals sector just yet!
Watch this space!