Showing posts with label INDIAN EQUITY. Show all posts

Friday, August 23, 2013

DHIRENDRA KUMAR ON THE SAD STATE OF THE INDIAN ECONOMY

A Long and Dark Journey

Our country’s economy is being run aground, and there’s little serious effort to revive it
LINK:

Here's an excerpt from his article

Let’s use a medical analogy for what is happening to our country’s economy. The global financial crisis of 2008 was like an infectious disease that spread rapidly. India was hit too, but we probably had better immunity than many others. On the other hand, India’s current economic crisis is like a cancer. Treatment is possible but it’s difficult and expensive and has a lot of harmful side effects. But the biggest problem is the doctor himself seems disinterested in the cancer. Instead, he and his assistants seem intent on fighting other incidental symptoms with treatments that will actually make the cancer worse.

However, the decline of the rupee is merely one symptom of the underlying disease. The core problems are that on one hand, the government’s expenditure is out of control and on the other, we are less and less competitive in the world. There’s a cascade of causes and effects that are interconnected in a web in which we are trapped. Excess government expenditure means huge borrowings. Government borrowing crowds out industry. Massive consumption expenditure by the government drives up inflation. Poor infrastructure and labour quality constraint supply and therefore make inflation out of control. High domestic inflation means that to remain competitive, the rupee must fall.

The relaxation of FDI limits is based on the notion that low limits are what is holding back investors. This is a fantasy. Poor infrastructure, corruption, red tape and a hostile regulatory and tax environment are the actual problems. If ownership limits were the issue then we wouldn’t have seen so many Indian business houses so interested in investing abroad.
I’m sorry for taking such a pessimistic view, but there are only a few silver linings and things will get worse before they get better.

Tuesday, August 20, 2013

USD INR - THE DOWNWARD SPIRAL INTENSIFIES

The Indian Rupee  has continued it slide versus the USD.
The INR is down almost 19% vs the USD since the beginning of May 2013!

Inaction and lack of reforms by the government have continued to compound problems of food inflation and currency depreciation.

At the present time, local investors are faced with volatile and mostly negative returns in both the equity markets and also the Indian Debt market, which has been severely rattled by sharply rising Government bond yields.

The only asset class that has managed to outperform and provide a hedge to local investors is GOLD.(thanks to a currency depreciation)

EXCELLENT POST FROM ZERO HEDGE:

Indian Rupee Collapses - Worst Day In 20 Years | Zero Hedge

The Indian Govenment has been steadily raising import duty on gold, in its continuing effort to rein in the current account deficit.

Watch this space. 
As valuations in the Indian Equity markets start to look attractive, remember that the country now faces a rather tricky situation of slowing growth, steady/persistant inflation, and a weak currency.

GDP growth rates of under 5% are now a distinct possibility.

While a sub 5% growth rate may appear robust to readers in the developed world----in emerging markets like India, it is extremely worrying.

Unemployment and non performing bank loans will be  serious problems over the next few years, if we are unable to get the economy back on track.


The inability of the RBI to cut interest rates (due to a rapidly depreciating currency and a rising current account deficit) will add to the woes of a struggling manufacturing sector. Stock prices of companies in the engineering / capital goods space are now trading at 8 year lows, and hopes of a recovery look bleak at the moment.

The Banking sector too has faced a drastic sell off in stock prices since May 2013. Public Sector banks will face considerable stress and even at todays discounted valuations, they still remain a high risk buy- meant only for those who are ready to weather more turmoil in the sector.

Perhaps, private sector bank stocks need to correct too, as expectations of growth are adjusted downward. Many private sector banks trade at expensive price/book ratios even after the initial sell off

Lastly, FMCG (Consumer staples), Pharmacaeuticals, and Information Technology (IT Services) remain the last pillars of strength.
Buying in these sectors should be done with extreme caution, as valuations may not leave an adequate margin of safety for the investor. 

These sectors will continue to relatively outperform the benchmark indices, as they function with nominal government price controls (FMCG) and in the case of export oriented Pharmacaeuticals and IT companies - are beneficiaries of currency depreciation.


Monday, September 3, 2012

RUCHIR SHARMA - On INDIA'S GDP, INFLATION & ECONOMIC OUTLOOK


Ruchir Sharma | Morgan Stanley
'Ratings downgrade possible; inflation worrying'

"""""Something similar is true of Indian policy as well that what we need to do first is stop doing any harm. So, even the first objective now seems to be that let's go back to where we were on February 28 before we had a terrible budget, lets reverse all those steps first then lets take it. In India's case its about lets stop doing any harm, lets reverse some of the damaging stuff that we have done over the past few months and not expect any big bang reforms which is going to transform everything in a second because those sort of sentiment swings are never healthy.
Can monetary policy do something about inflation or it can't?
This is where the intellectual debate goes on. I really think that the bigger fault lies with our spending habits rather than to do with the interest rates policy out here. You cannot keep spending as you said you can’t keep writing cheques which a country can’t cash. The average spending in India has been growing government spending about 15% a year ever since the UPA came to power in 2004 before that it was more like 10-11%. To me that is the fundamental problem.  """""""

Monday, August 27, 2012

INDIA'S NET FINANCIAL SAVINGS RATE CONTINUES TO TREND DOWNWARDS

As the Indian consumer consumption boom continues, a combination of moderating growth rates, high inflation and low real rates on investments is taking a toll on India's Net Financial Savings rate. 


""According to preliminary estimates released by the Reserve Bank of India (RBI), net financial savings moderated to 7.8% of GDP in F2012 from 9.3% of GDP in F2011 and 12.2% of GDP in F2010.
Net Financial savings comprises cash investments, deposits with banks and non bank companies, investments in shares, debentures, mutual funds, small savings and also life insurance, provident and pension fund


RBI attributed the decline in net financial savings to persistently high inflation, leading to low real rates on bank deposits and small savings funds, coupled with uncertain global environment adversely impacting equity market returns, leading households to favour investments in valuables such as gold. In addition to these factors, we believe slower urban job creation and income growth would also have affected the rate of household savings."""

LINKS:

Friday, August 17, 2012

INDEPENDENCE DAY -15.08.2012 - INDIA @65


Well, after a year of policy inaction, high inflation, and slowing growth; it's now 65 years since Indian Independence.

Below are links to a couple of articles that are well worth a read.
Ruchir Sharma and Swami Aiyar have an interesting take on Indian Independence and the Outlook for India's economic growth rate amidst a slowing and deleveraging global economy

RUCHIR SHARMA :
India's breakout path: It needs to break global growth script, not slavishly follow it


SWAMINATHAN AIYAR:
Independence Day: Why Partition was a good thing for India

Thursday, July 26, 2012

CRUDE OIL OVERVIEW -BUSINESS LINE NEWSPAPER - July 1, 2012

The Sunday Business Line Newspaper from ''THE HINDU'', on July 1, 2012 discusses the average price of an Indian Basket of Crude Oil and compares $/barrel and INR/barrel prices.

Crude Oil imports account for just over a third of  India's imports; and thus high Crude Oil prices coupled with a weak INR have resulted in persistent inflation despite high interest rates set by the RBI.

Also, this situation has resulted in rising government Petroleum (Oil sector) subsidies as the Indian Government continues to heavily subsidize retail fuels like Diesel, Cooking Gas and Kerosene.

If the price of Crude Oil refuses to correct despite a slowing world economy, and if the Indian Rupee fails to regain lost ground vs the USD; the Indian Government will have to rethink its policy of "unsustainable" Petroleum sector subsidies and instead plan for a gradual move to market driven - prices for fuel sold by the Oil Marketing companies.

Tuesday, July 17, 2012

Y.V. REDDY - ON REGULATION, BANKING AND REFORMS


Link: http://economictimes.indiatimes.com/opinion/interviews/banks-have-to-be-board-driven-government-should-not-dictate-their-operations-yv-reddy-former-rbi-governor/articleshow/15011122.cms?curpg=2

"Banks have to be board-driven, government should not dictate their operations: YV Reddy, Former RBI governor"

Some edited excerpts:

There is growing criticism, both internally and overseas, about policy inertia and inept economic management by the government. What is your assessment and what, in your view, should the government do to swiftly address some of the issues on the economic front?

I cannot comment off the cuff. But I will draw back and say what IG Patel's perception of reform is. One major point he made was about the distinction between macroeconomic management and micro-sectional reforms. Macroeconomic management has, by and large, been good in India. Yet some reforms are needed. His emphasis was on sectional reforms and efficiency of the reforms.

The broader aspect is that three areas were not sufficiently addressed. One is the issue of corruption, second is confidence of civil society, and third is higher education. So, in a way, we should not think that if you keep deregulating, it is reforms.
Then there are issues in the global economy. Does that mean we should not move forward? I don't think reforms as contemplated before the crisis should be blindly carried forward. In considering reforms, efficiency should be a criterion. Macroeconomic balance is important. Macroeconomic imbalances create instability. We require growth impulse and it depends on savings and investments and productivity.

Recently, Dr Rangarajan said that even without changing the banking regulation laws, the RBI could consider issuing bank licences. Do you agree?

No, I don't agree. Purely from the global crisis situation, all over the world, they are very strict from the regulatory perspective. Even before they experienced the crisis, the Reserve Bank had requested some regulatory framework for regulating the banks, that is absolute necessary minimum.

So if the government is not able to give minimum power to the regulator, it is inappropriate to give any more licences till the law is changed and the regulator has enough regulatory (jurisdiction/freedom), more so because the type of entities that are likely to get the banking licences.

You already have Indian corporates in the mutual fund industry, they have got interconnected insurance companies, they have interconnected NBFCs, and then if you add banks, then it going to be extremely difficult for a regulator. The whole conglomerate structure - it is not only going to be a financial conglomerate, but an industrial-cum-financial-cum-banking conglomerate - becomes too big to regulate.

Monday, May 7, 2012

Indian Banking - Cases of Debt Recasts and NPAs

Here is a Newspaper Article on  "Rising cases of debt recasts & NPAs" by Abhijit Lele & Ranju Sarkar, from the Business Standard Newspaper in Mumbai.

Link:
Rising cases of debt recasts & NPAs ( check out the graphics pdf for charts and more info)
I've also attached adcanned copy of the article below

As some over leveraged companies work their way out of some rather sticky situations, it's another reminder to investors to check exactly how leveraged some of the companies they invest in really are.

High interest rates in India coupled with the reluctance of the inflation battling "Reserve Bank of India", the country's Central bank to lower interest rates; will mean that we could be in for some more restructuring of NPAs going forward.

Monday, April 30, 2012

INDIAN ECONOMY AND INDIAN EQUITIES - STORMY WEATHER UP AHEAD

The Bullish Bear Blog has always been a long term bull as far as the Indian Economy and Equity Markets are concerned.

However, the ongoing policy paralysis over the last couple of years, further compounded by the scams and corruption issues have started to make even ardent bulls like myself a bit nervous and uncertain of India's long term outlook.

Sectors  that need a quick resolution to underlying issues include

1. Power Sector -  Coal Linkage issues have left many newly built/under construction power plants stranded. Troubles with increased royalty on imported indonesian coal has resulted in UMPP plants like the Tata Power plant at Mundra operating well below full capacity.

2. Fossil Fuels  - 

Oil and Gas - Pipeline tarrif pricing, Gas price policies, Deregulation of prices of retail fuels such as Petrol, Diesel, Kerosene, and LPG

Coal Sector - Disputes over coal block allocations, pricing of coal and arm twisting of the Coal behemoth Coal India - to sign Fuel Supply Agreements with power producers has added to the ongoing chaos in the sector.

In the long run, markets will have to move towards a market oriented pricing scheme, as the current system of subsidising fuels and end user prices is neither sustainable or viable.

3. Fertilizer Policy - Lack of proper implementation of policies has resulted in soil imbalances as farmers step up Urea usage as a substitute for more expensive DAP (Phosphate based fertilizers)

3. Telecom Sector- 2G spectrum scam and now pricey 2G auction base prices have left both investors and operators uncertain about fresh investment in the sector.

In light of the above issues, I think Akash Prakash's article in the Business Standard Newspaper Mumbai - 27-04-2012 is an excellent read, and perfectly sums up the current predicament of the every prospective and invested Indian Equity Investor.


MUTUAL FUNDS IN INDIA - AUM -City wise contribution

Here is a good article on the Assets under Management (AUM) by Mutual Funds in India, giving a city-wise contribution. ( BUSINESS STANDARD NEWSPAPER, MUMBAI - 19/04/2012)

Clearly, there is a lot of growth potential  in this underpenetrated market.
So far, just Mumbai and New Delhi make significant contributions to the Assets under Management, with Mumbai contributing the major share.

Watch this space!

Saturday, January 7, 2012

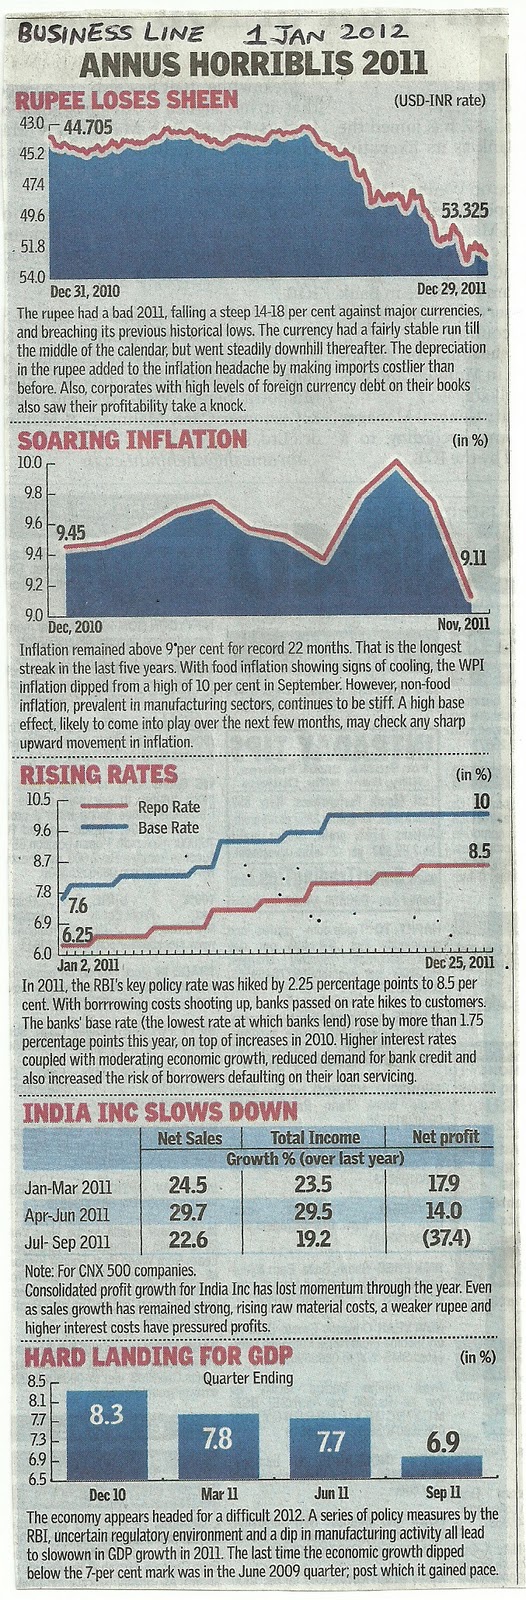
INDIAN EQUITIES -DEBT WORRIES SURFACE AS THE ECONOMY SLOWS

As the Indian Economy slows, a number of Indian Corporates may find that they over-stretched themselves while the going was good, and are now saddled with heavy debts to repay.

It's not that borrowing for business expansion is a bad thing in itself, it's just that some over-leveraged Corporates will struggle with debt servicing in 2012.

Some sectors that come to mind are the Airlines, Oil services, Ship- building and infrastructure.


Investors must keep in mind that although many stocks in these sectors trade at record low valuations, the Risk -Reward ratio may still not favour investors at this stage.

Remember some stocks have been beaten down for well deserved reasons, and investors must analyse their own risk return profiles before jumping in now.

In my view, many companies will need some debt restructuring before they can trurn things around.
This could mean that the banking sector too could take a while to recover, at least until interest rate cuts expected in the near future ease the liquidity concern of some cash strapped corporates.

Invest wisely!

Indian Equities - Looking Back at 2011 - PART 2

Here are a couple more articles to round up our look back at 2011!

Monday, January 2, 2012

INDIAN EQUITIES - LOOKING BACK AT 2011

Here are some articles from last year that I think are worth a read.

Indian Equities have been faced with a toxic combination of Policy inaction, high interest rates, a very weak Indian Rupee and waves of instability from western markets, primarily the EU.

The articles below provide some interesting views on the Outlook for 2011. Mukul Pal's contrarian outlook, highlights the point that beaten down sectors that have been written off by Mr. Market could surprise us in 2012!

Saturday, November 26, 2011

INDIAN RUPEE : FOREX FLUCTUATION & INDIAN POLICY REFORMS

Here is a good article from today's Business Standard Newspaper in Mumbai.
Rupee fall pares India Inc's profit by a fourth in Q2

If the weakness in the INR continues, upcoming FCCB redemptions, USD denominated foreign Currency borrowings and the rising cost of imported raw materials will continue to add to the woes of Indian Corporates in the results of the third quarter.

Many blame the INR weakness on FII selling in the Indian Equity markets.
While FII selling has played its part, I feel the ongoing Government policy malaise and concerns over the Government's Fiscal Deficit continue to weigh down the INR.
Currency downgrades by the Rating Agencies will add to the downward pressure on the INR.

Also, it's about time that the Indian Government gets down to implementing many long delayed reforms.

Some sectors in dire need of reforms
POWER SECTOR - Poor financial health of State Electricity Boards (SEBs) is forcing them to resort to  load shedding of power even as Power producers are left with surplus power that they are unable to sell. These SEB's must move towards a market determined pricing of power sold by them to distribution companies.
Merchant Power sales and Power trading are also facing many unresolved policy issues.
Under construction Ultra Mega Power Projects also face uncertainities due to fuel linkages (read: Coal allocation issues and royalty issues on Coal imported from Indonesia).
.
MINING SECTOR - Confusion over a proposed Mining Tax, profit sharing with locals displaced by Mining projects, Land acquisition delays and mining scams and corruption have delayed many Mining & Smelter projects.
.
FERTILIZER SECTOR - Partial implementation of the Nutrient Based Subsidy Scheme (NBS) and the delays in decontrol of Urea pricing have compounded the problems of the sector. Heavily subsidised Urea fertilizer has resulted in farmers opting to use Urea over DAP fertilizer. Excessive use of Urea has upset the balance of soil nutrients and has thus resulted in lower crop yields.
Any further delay in decontrolling Urea fertilizer pricing will add to government subsidies as the government continues to import Urea shortfall from overseas. A weak INR will add to the cost of imported Urea fertilizer.
.
TELECOM SECTOR - The ongoing 2G scandal and corruption cases continue to dominate news in the telecom sector. What the government must take a look at is reforming regulations that will promote consolidation in the Telecom sector. Recent issues of 3G roaming should also be clarified by the TRAI and the government, to avoid any further uncertainty in this sector.
.
AVIATION SECTOR - A combination of ''below cost '' fares by Air India,  record high ATF prices, ultra competitive air ticket prices, and record high debt of the airlines themselves has resulted in some serious structural problems in the Indian Aviation sector. FDI limits in Indian Aviation will have to be liberalised and a more viable tax structure on ATF will have to be worked out, if the existing carriers are to survive as going concerns. Perhaps the government will have to look at the development of "Low cost airports'' from which the Low Cost Carriers can operate, given the expensive Landing and Parking Costs at the country's main airports.
.
OIL SECTOR - Massive delays in implementation of a clear and viable Gas Pricing policy is delaying further development of Oil and Gas Blocks in the KG Basin. Until this vital issue is resolved, Fuel Linkage issues of Power & Fertilizer Plants will not be resolved. The longer it takes for this Gas to reach the market, the more will be the delays of construction of new Power and Fertilizer Plants.
Also the" retail fuel pricing - under recovery problem" of the Oil Marketing companies (OMCs) remains unresolved. Massive subsidies on retail fuels sold by the OMCs have weakened their finances over the last decade.
A weak INR+ high Crude Oil price is adding to the under recovery burden of the OMCs.
If the government fails to move to a market determined pricing mechanism for Retail fuels soon, these OMCs will soon need to be bailed out by the government.
.
All in all, it's about time that the government takes a step forward, and gets downto resolving these 'bottle neck' issues that are plaguing the Indian Economy at the moment.

If some of the supply side issues are worked upon, then perhaps the subsequent drop in inflation and an improvement in the government's fiscal deficit targets, will help the INR to regain some lost ground.

Tuesday, November 22, 2011

THE INDIAN RUPEE - WEAKNESS CONTINUES.....

The continuing weakness of the INR vs the USD is starting to worry both investors and regulators alike. Negative FII fundflows in the Equity markets is adding to the weakness of the INR.

At a time when inflation continues to be persistantly high, a weak INR will add to India's already increasing Crude Oil import costs.

The Equity Markets in India are preparing themselves for forex loss announcements from companies that import their raw materials and those that have large Foreign Currency borrowings.

We are now surpassing levels last reached during the heights of the financial crisis in the first quarter of CY 2009, just after the Lehman Crisis!

Energy and commodity prices were far lower in March 2009 than they are right now; so the Government and especially the Central Bank (R.B.I) will have to come up with some strategy to stabilize if not support the INR at current levels.

WATCH THIS SPACE!

Friday, July 15, 2011

INDIAN EQUITIES - AN UPDATE

Here's an article titled - 'A Two - Tier Market' by Akash Prakash from the Business Standard Newspaper dated 8th of July 2011 - Mumbai edition..


He addresses the issue overvaluation of the consumer-staples sector and highlights the difficulties of buying high-quality companies at a reasonable price in the Indian Stock Market.
.


Currently, many consumer staple stock trade with PE ratios of 30-35!
.


On the other hand, investors continue to shy away from industries that are in need of capital, mainly due to concerns of poor earning visibility. Many infrastructure companies are facing great difficulty in raising capital.


The article is a fantastic read.

Tuesday, June 28, 2011

INDIAN PETROLEUM SECTOR SUBSIDY CONUNDRUM

The Government of india finally implemented a long overdue price hike in diesel, LPG & Kerosene.

Even as inflation statistics continue to remain uncomfortably high, the government had to finally bite the bullet!
The government must come up with a long term viable pricing policy for petroleum products.
The Oil Marketing companies like BPCL, HPCL & Indian Oil cannot afford to keep subsidizing retail fuel prices. Currently their profitability is dependent on Oil bonds - a government handout!
.
Upstream marketing companies like ONGC & GAIL are helping the government to bear the losses from under recoveries, and this is preventing them from investing in Oil Assets and building Oil & Gas infrastructure like gas pipelines etc
.
The government will also have to step up investment in public transport infrastructure like metro rail projects & urban bus transport networks. Perhaps such a move will help reduce traffic congestion and in the long run reduce our heavy dependence on petrol and diesel.
.
Lastly I would like to point out that a large chunk of the levied retail fuel price on fuels like petrol and diesel, consists of govenment taxes that does not go to the oil companies, but is a major source of government revenue!
.
It's time that a truly sustainable long term fuel pricing policy is formulated.
With Crude Oil prices that continue to trade around $100/barrel, the government must come up with such a policy as soon as possible.
Below is an announcement by the Govt of India in the Economic Times on the 27th of June 2011.

Sunday, December 19, 2010

INDIAN EQUITIES : FII & Domestic Institutional Fundflows

2010 has been a good year for Indian Equities. The FMCG (Consumer staples ) sector, Auto sector & Banking sector have performed well this year. Valuations are no longer cheap, and the margin of safety for investors has narrowed substantially.

Link - Domestic institutions turn cautious, go on selling spree ...
As usual, FII fundflows continue to dictate market direction, but as the above article points out, Domestic Institutional investors - Mutual Funds are booking profits.

Friday, December 17, 2010

A TALE OF TWO INDIAS !

The Economist magazine recently published an article regarding India on 25.11.2010 titled

Graft in India - Rotten to the Core? Coping with the aftermath of a massive scam !!!
And who's to say that they are off the mark as far as the story goes.


We have been on a never ending roller coaster of scams.

  • IPL - Cricket scam -issues regarding benami -ownership structures of teams
  • Commonwealth games scam.
  • Adarsh Building scam in Mumbai - Illegal Building on Army land
  • Telecom 2G scam - That's a mega one!
  • Public Sector bank officials involved in a loans for bribes scam.
  • Stock price rigging scam being investigated by SEBI.
  • Nira Radia tapes - involving journalists, industrialists etc!

So we have massive wealth disparity, income inequality, corruption, rural poverty, poor infrastructure and then we have on the other hand an ecomnomy that's doing fantastically well, while the world economy is still reeling under the strain of slowing consumer consumption and record debt levels.


.
.
.
.
.
.

.
.
.
.

..
.
.
..
.
..
.
.
.


While its going to be a never ending discussion about the politicians, industrialists and other individuals involved in these scams, there are some facts and lessons that an investor in Indian markets can take away from this mess.

  • While the Indian Economy does present a fantastic investment opportunity to both Indian and overseas investors, it can be bumpy ride at times.

  • While the Indian government continues to move slowly on / ignore vital issues like wealth disparity, rural poverty, overburdened infrastructure and the poor state of primary education and healthcare facilities across India, they must realise that this economic boom cannot continue unless they start to tackle the above mentioned critical problems and target "inclusive growth".

  • Remember to curtail investments to firms where the management has a credible track record and takes care of the interests of all stakeholders concerned - & not just themselves! You may come acoss an interesting investment opportunity, but if the management has a dodgy track record, just stay out!

  • If SEBI fails to rein in the Equity market scamsters, it will result in a massive blow to SME (Small and medium enterprises) businesses in India. The SMEs are the ones most affected by these stock rigging scams because a tightening of bank credit across the SME sector will deny working capital loans to many deserving and good quality small cap companies in India

  • The incredible progress that has been made by Corporate India has been made inspite of our politicians and not because of them!

  • While I'm not condoning the massive, almost blatant and shameless corruption here in India; we live in a world where politicians in most countries are no better than the ones we have here. It may be less blatant but sadly,corruption goes on!

  • There is incredible corruption,short termism and lack of leadership in global politics today.As someone rightly said, " The people who want to be in politics are not the people whom you want to be in politics". No politician is willing to fix a problem that he can kick further down the road, an example being the *crazy debt crisis* facing the western world today! Imagine asking consumers who have no savings to start overspending and re- leveraging again - Thats both WRONG & insane!

  • Lastly, remember that the prudent investor does not chase an over extended stock market rally. Remember to wait for pull backs and always look to invest in good quality stocks, with managements that have an established track record!

TELECOM SECTOR INDIA : CONSOLIDATION TIME

Below is an article from the Economic Times - 4 December 2010.
Link:
All new telcos have less than 50% active users, finds Trai - The ...

The Pre-paid/ Pay as you go segment dominates the mobile phone telecom sector in India.

With record-low tariffs and cut throat competition, telecom companies are hoping to regain earnings traction via 3G services!

Furthermore, we may be headed for a 3G price war as well.
The percentage of active subscribers is far too low in the case of many of the new entrants. Some of the new players will gradually find the current tariffs unviable for their business models, and a consolidation is likely.

This is clearly an overcrowded market. In the meantime, expect the established incumbents to aggressively defend their market share. This will result in reduced profitability in the near term, until an inevitable consolidation occurs/ some players exit the market altogether.